The Uncapped Broker · For Medicare brokers
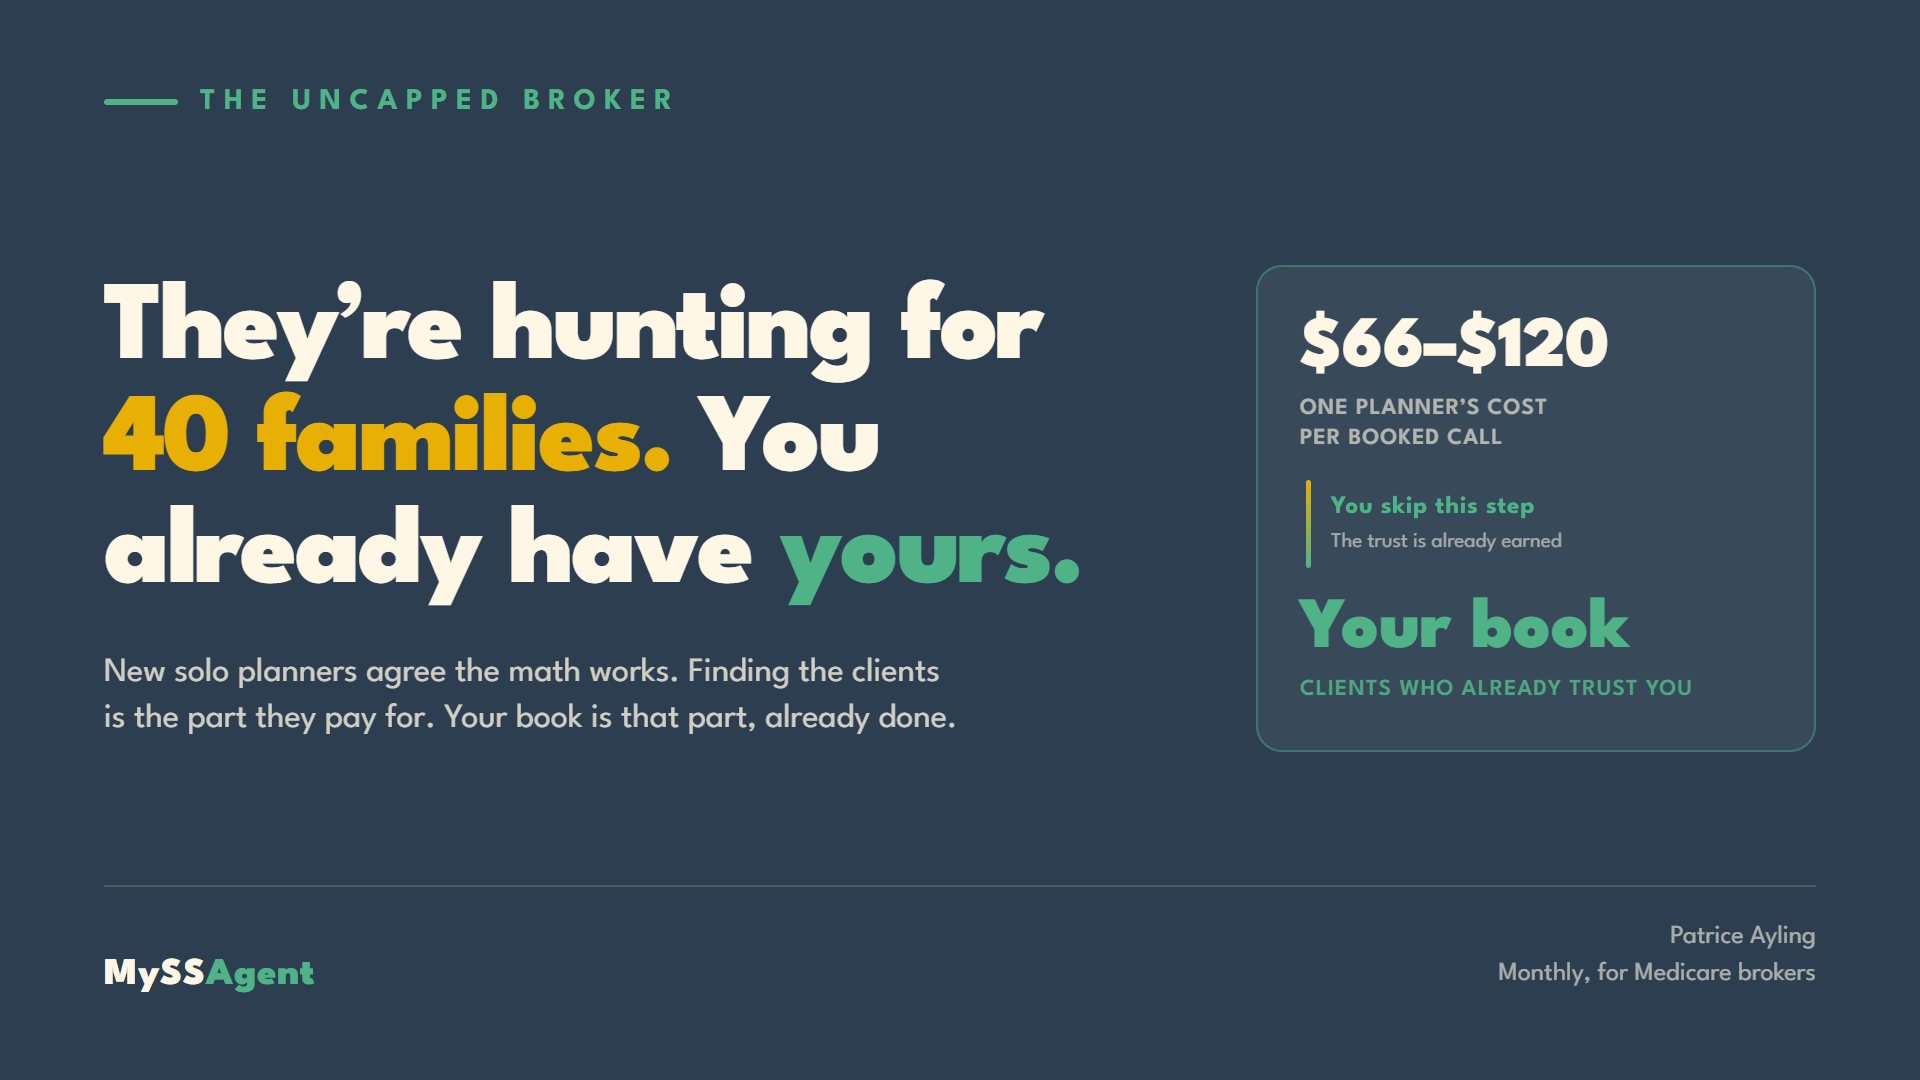
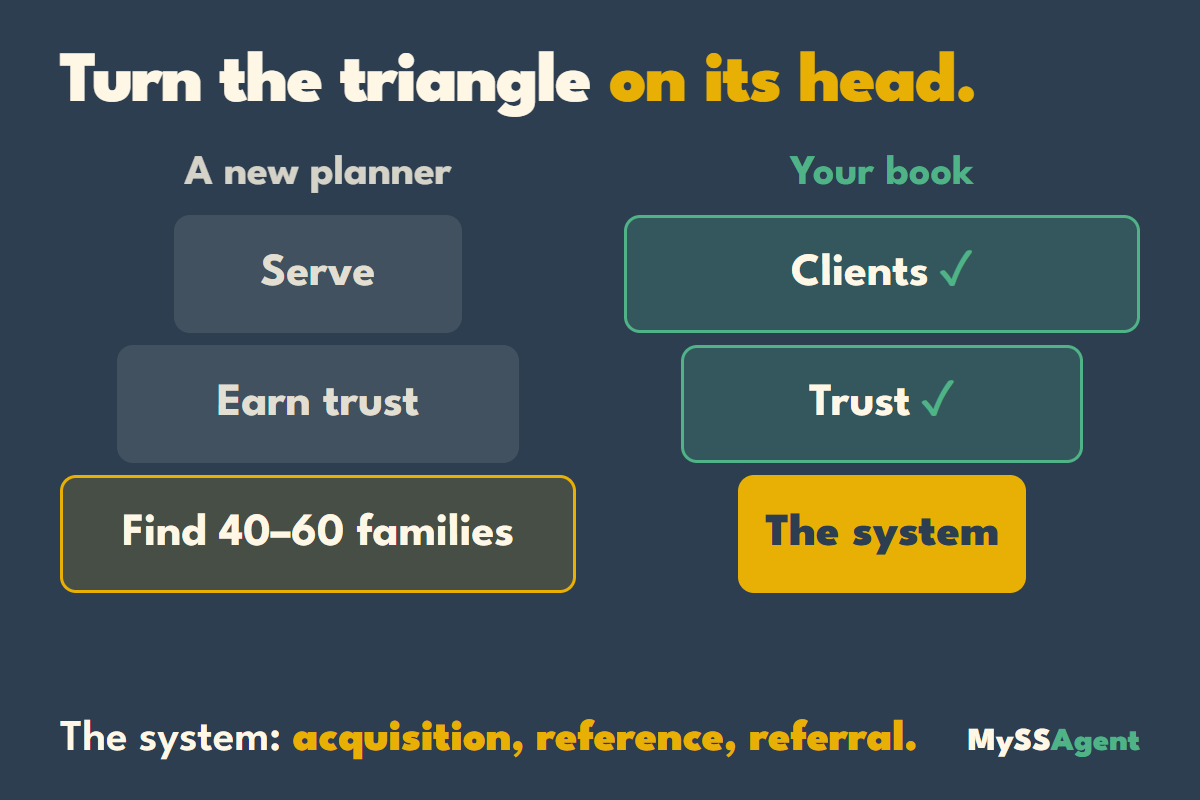
This month a post on r/CFP, the forum for financial planners, argued that this is the golden age to go solo. Launch a firm for about $5,000. Run it on $15,000 to $20,000 a year. Serve 40 to 60 families.
The planners who replied mostly agreed with the math. Then reply after reply landed on the same problem: finding those 40 to 60 families. One planner said the only thing that had worked was paid ads, at $66 to $120 for every booked call.
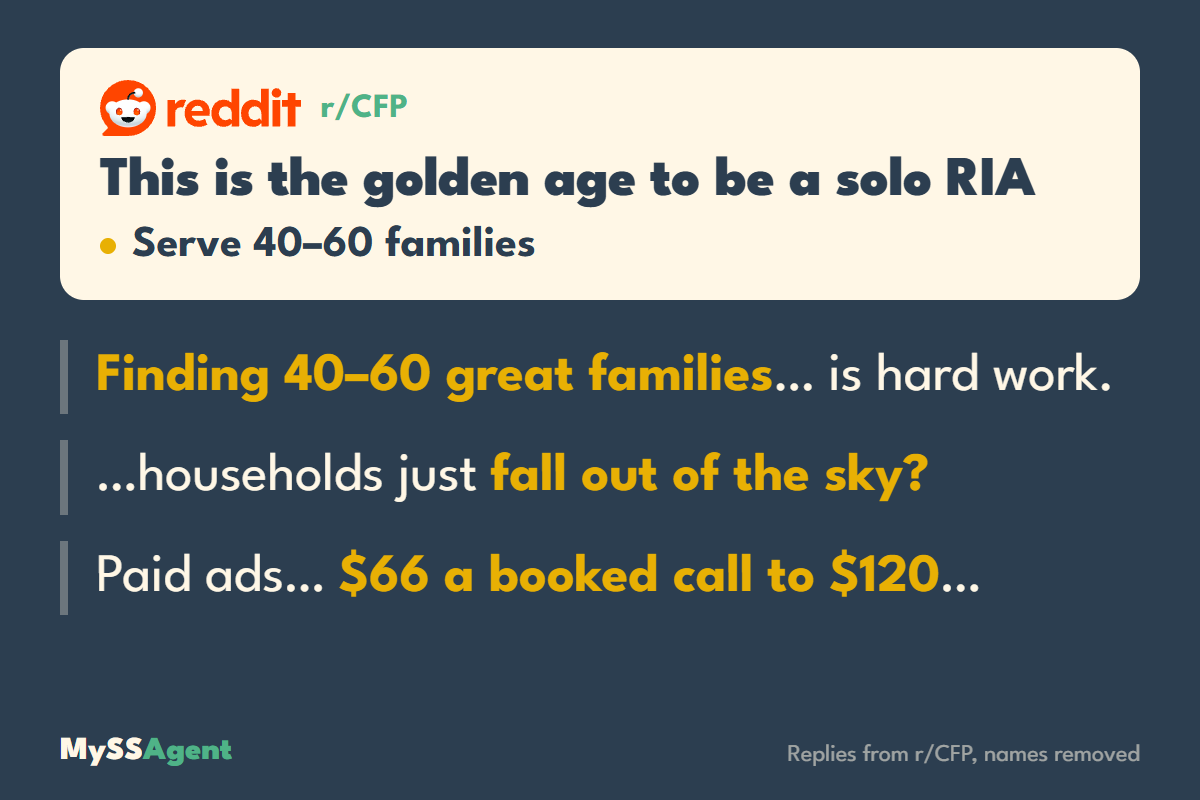
I read that thread as someone who works with Medicare brokers, and one thing stood out. The part they are paying to build is the part you already have.
Every client you’ve enrolled trusted you with a decision that mattered to them. Most of them hear from you every year. A new planner would spend real money to sit across the table from any one of them.
Commissions are capped. Your book is not captive. What most books don’t have yet is a second service that pays you.
Social Security is its own decision, on its own calendar. Benefits can start at 62. Full retirement age is 67 for anyone born in 1960 or later. Delayed credits stop at 70. Each month in that window pays a different amount for life, and for a married couple the choice carries over to the surviving spouse.
Your clients in their sixties are working through that question whether or not anyone helps them. It sits right next to the Medicare conversation, and it isn’t Medicare. That makes it a separate service, in a separate appointment, for clients who already trust you.
Charge for it. Set a flat fee per household. A license that covers 25 households a year works out to under $80 each, so the margin is yours to set. That is income from your existing book that no carrier commission schedule touches.
Or roll it in. Run the review free for a client about to turn 65, or for a 62-year-old on your ACA book. ACA, then Social Security, then Medicare: the same client, three decisions, and you’re the one who helped with all of them. That’s the long game on enrollment, and on renewals.
Either way you’re diversifying, and you’re doing it inside relationships you already own.
Pull the clients on your book who turn 62 through 66 in the next twelve months. Open with one question:
“Have you decided when you’ll start Social Security?”
Most haven’t. Plenty haven’t looked at their statement in years. You may be the first person who asked.
The planners on that thread are paying to find their first 40 families. Yours are already in your book.
That is what this newsletter is for. Once a month, how to turn Social Security claiming advice into awareness, income and client retention.
Patrice Ayling
Sources
Educational material, not tax or legal advice.