For RIA firms and planners
Social Security planning software for advisors
Client retention wins.
Proactive Social Security communications to every household in the claiming window — about a minute each, not an afternoon.
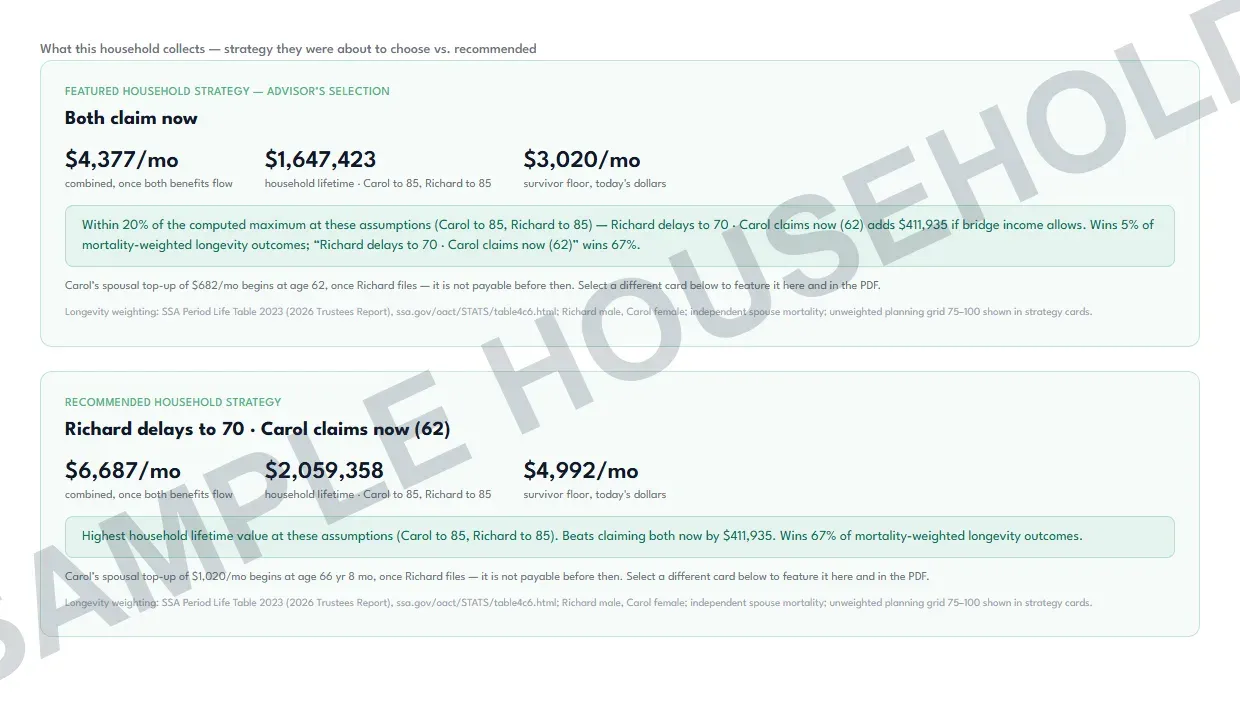
Every monthly claiming age from 62 to 70, run against the household’s own record. Then a dollar page your client can read, with your firm’s name on it.
more assets top-performing firms took from existing clients than their peers — Schwab 2026 RIA Benchmarking Study.
of firms name capacity as the top constraint; the median firm serves 235 households — Dimensional 2025.
monthly claiming ages, each run at three longevity horizons — every combination computed in code.
dates already in every CRM — the 62nd birthday, full retirement age and 70. Three reasons to write, no manufactured urgency.
The comms piece
A reason to touch base that doesn't eat the day.
Firms with better client communication keep the book and grow it. The hard part was never the willingness to reach out — it was having something worth sending to every household, without burning an afternoon to produce it.
You already know the date
Every household’s 62nd birthday, full retirement age and 70th are in your CRM. That is the reason to write — no timers, no manufactured urgency.
- 62
- FRA
- 70
About a minute per household
Run the whole mass-affluent middle of the book in an afternoon, not a quarter.
The dollar page is the message
Co-branded, sent, and the conversation that follows is yours.
Why a firm that earns on AUM bills for this
Fees
A repeatable, billable service across the mass-affluent middle of the book — not just the household that thought to ask.
Clients
Retirement puts assets in motion: 39% of IRA-owning households changed financial-services providers in their most recent rollover, and 63% gave consolidation as a reason. Reaching out with the claiming answer is how you are in that conversation early.
Book
A delay strategy means bridge assets someone has to manage. That someone is you.
The money is in the middle of your book
Retention is not the problem. Median RIA client retention has sat at 97% for a decade, so you are not losing these households, you are carrying them. The question is what the mass-affluent middle costs to serve against what it pays.
229
households in the median RIA's individual book. About 160 of them are not high-net-worth.
15.5 hours
to build one plan, for teams earning under $5,000 a year per client. The hours barely fall as the revenue does.
$400
the published floor for a claiming analysis. It goes on the engagement letter as its own line.
That is why the complete claiming answer gets built for the household who asks for it and not for the other hundred and fifty. Premium covers 150 households. The median firm’s non-HNW book is 160, and the band was cut from this same dataset.
Book composition: our own analysis of the SEC Form ADV file, 10,497 firms serving individual clients, pulled July 2026. Plan hours and retention: Kitces Research and Schwab RIA benchmarking. Analysis fees are published advisory rates, which start at $400.
identified for a client by a credentialed Registered Social Security Analyst® — the founding case. Individual results vary.
of retirees in a United Income (2019) study claimed at the optimal time. The rest left an estimated ~$111,000 per household on the table.
Americans turn 65 every day through 2027 — and each one makes a permanent Social Security decision.
How many afternoons is your book?
A complete manual claiming answer could cost an afternoon, so it only happens for the client who asks. Move the sliders to see what the same book costs in hours — and how much of that time becomes proactive communications instead.
Hours and counts only. We do not print a revenue-per-client figure — we are not instrumented to claim one.
- +358hours reclaimed this year
- 360 hours done manually. The same book runs in about 2 hours.
- 120household analyses you could run — and bill
- One analysis is one household. Couples count once, and re-runs for that household are free.
- 120conversations you could open
- One dollar page is one reason to write — on a date already in your CRM.
- Premium covers it — 150 household analyses a year.
- See the bands and the expert layer →
Compared with other Social Security software
| What you get | Manual | Planning-stack tab | MySSAgent |
|---|---|---|---|
| Every monthly claiming age, 62 to 70 | An afternoon | Whole ages, one person | About a minute |
| The survivor line on screen | If you remember to run it | Rarely | On every household |
| The client’s real earnings record | Re-keyed manually | A typed PIA | One click, no SSN |
| A dollar page to send, under your brand | Your own document | Inside a longer plan | Every run · co-branded, or white-label on Premium |
Moving your practice off another tool? Our SSAnalyzer alternative page puts the two side by side.
What compliance and your partners will ask
"We need SOC 2."
Our SOC 2 Type I report was issued by an independent CPA firm as of July 31, 2026. A Type II examination is under way.
"Couldn't someone recreate this with a public LLM?"
An LLM can tell you about Social Security; it can't tell you what your client's record is worth. Our math is a deterministic rules engine — 291 combinations, the same answer every run. The nearest shortcut is pasting a client's earnings record into a public model, and your compliance department has a view on that.
"The optimum is always 70 — I don't need software for that."
At a 95 planning age, nearly everyone optimizes at 70. The value is how the answer moves: the same household optimizes at 65 at a 76 horizon and 70 from 84 up. That spread is the conversation.
"It won't talk to eMoney / RightCapital."
The hand-off block gives you own-record monthly figures at 62, FRA and 70 per person, copy-ready for your planning canvas. Integrations are on the roadmap; we won't claim one that isn't live.
"We don't get paid on Social Security."
Right — which is why the module in your stack never got built out. This is a service you can bill for across the mass-affluent middle of the book, and the delay strategy it often recommends means bridge assets someone has to manage.
Still have one? Ask me.
I run the B2B lane and talk to every advisor who comes through the door. Book 30 minutes — if it’s not a fit, I’ll tell you.
Patrice Ayling · Founder, MySSAgent
Pricing
Where does your firm fit?
Priced by households served, never advisor seats.
One license. A yearly bank of household analyses, sized to the slice of your book in the claiming window. Two bands and an enterprise lane. One analysis = one household. Couples count once, and re-runs for that household are free.
Professional
$1,990 / year
or $181/mo billed monthly — annual saves one month
25 household analyses a year — under $80 per household
The solo practice band. Cover the clients deciding this year.
- Full optimization engine — the complete SSA claiming rulebook, every claiming age modeled
- One-click client earnings capture via the Chrome extension
- Client-ready PDF reports, co-branded with your firm logo
- Spousal coordination and the survivor line, on every analysis
- Maxine, Your Social Security AI Agent — 24/7 in-meeting lookups
- Email support (business hours 9–5 EST)
Premium
Contact for pricing
150 household analyses a year — 6× the Professional bank
The firm band. The median advisory book fits inside it — with room to grow.
- Everything in Professional
- Quarterly strategy calls with your RSSA®
- Custom scenario modeling across the full SSA claiming rulebook
- Medicare integration planning — IRMAA guard on every analysis
- White-label dashboard and reports: your firm's brand on everything the client sees
- Priority support (same-day response)
Enterprise
Custom contract
Bands beyond 150 — sized to your firm’s whole book
Large firms, RIA networks and agencies. Priced by households served — never advisor count.
- Everything in Premium
- White-glove onboarding with a dedicated setup specialist
- Hand-off block for your planning canvas today; API integrations built as a partnership, scoped and priced to the deal
- Enterprise SSO/SAML and bulk advisor onboarding
- Quarterly business reviews with the MySSAgent team
- SOC 2 Type I report issued
- Dedicated account manager
- GTM Support — AI BPO Consulting
Grow through your band mid-year? Upgrade anytime and pay only the difference. Founding-cohort licenses purchased before August 2026 keep their original terms.
The expert layer: hand a case to a Registered Social Security Analyst®
Your license covers the software and the bank of household analyses you run yourself. A credentialed Registered Social Security Analyst® is available on complex cases — an option you exercise, priced per case, and worked for as long as the case takes to clear. Buy it per case, or bundle credits into your subscription.
Simple / standard case
$300 / case
Single record, straightforward timing question. Full analysis or support, worked end-to-end by an RSSA®.
Buy this caseCouple / spousal case
$550 / case
Two records, spousal coordination, deemed filing — the full married-household work-up, worked or supported end-to-end.
Buy this caseComplex case
$950 / case
Survivor, divorce, WEP/GPO history, or multi-benefit interactions. The cases that keep you up at night, worked end-to-end.
Buy this caseLive demo · no account
See it on a sample household.
Three fields. Straight into the case you pick.
No Social Security number ever enters the platform.
Every monthly claiming age from 62 to 70, computed in code — not generated by a large language model (LLM).
SOC 2 Type I report issued. Type II examination under way.
A Registered Social Security Analyst® available on complex cases.
One-click earnings record with our Chrome extension — live on the Chrome Web Store.
Prefer to talk it through? Book 30 minutes · Questions first? patrice@myssagent.com
Advisor reading from the MySSAgent library
The explainers advisors send clients most — sourced, and written for the client conversation.
- Optimal Social Security Strategy for Married CouplesCoordinate both records — spousal excess, survivor protection, and the claiming-age combinations that maximize the household's lifetime benefit.
- When “Delay to 70” Breaks: Who Else Is on the Earnings RecordAuxiliary benefits attach to the worker's entitlement, so nobody collects until the worker files — and the family maximum caps the total.
- Social Security & Medicare 2027: Every Number in One PlaceCOLA, Part B, IRMAA brackets, Part D, earnings-test limits — each figure labeled official or projected, updated in place as agencies announce.
- Social Security Claiming Timing and the IRMAA LookbackOne dollar over a threshold applies the surcharge for the whole year — decided by a tax return from two years ago. How claiming feeds in.
- Medicare Part D in 2027: What CMS ChangedCMS ended the Part D Premium Stabilization Demonstration and published the CY2027 bid figures. What it changes for this AEP.
- It Pays. Just Not on the Invoice.The retention math behind Social Security advice in an advisory practice: retention, referrals and the 92% to 22% memory gap, sourced.
- Business Owner Optimizer: Repair the Zero Years in Your 35-Year AverageSSA averages your highest 35 years of earnings. See what raising a low W-2 salary does to the benefit, with lead time.
- HNW Wednesdays: Smart Social Security for Affluent HouseholdsThe eight-part series on where default Social Security thinking costs affluent households, and what to do instead.
- The Social Security Planning Category Has No Dominant IncumbentMichael Kitces named it in his May 2026 AdvisorTech column. Our take, and what we are building.
- Credentialing Requirements for Social Security Claiming AdviceDoes an advisor or broker need a special credential to give claiming advice? The regulatory framework, for advisors and compliance officers.