For annuity and life insurance producers
Write more annuities and life insurance.
Add a Social Security claiming review to your practice. Each household sees its own numbers: the bridge income they need if they wait to claim, and the income that stops when a spouse passes.
The software has no opinion about products and never will. Product selection stays with you.
No account. No card. Your link arrives by email so you can get back in.
6½ yearsuntil he files
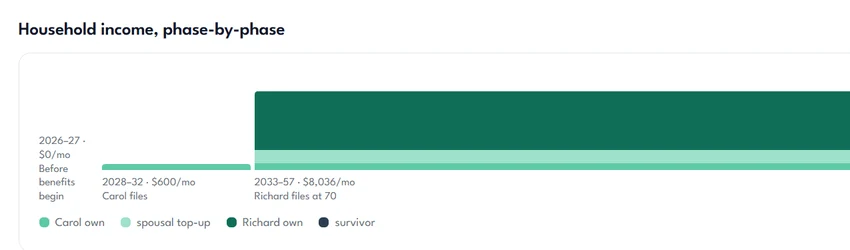
Waiting until 70 raises the check the survivor keeps by $1,671 a month. Until Richard files, the household has none of his check, and those years need income from somewhere.
$6,718 → $4,992/mo
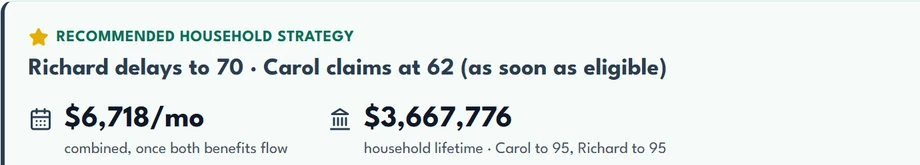
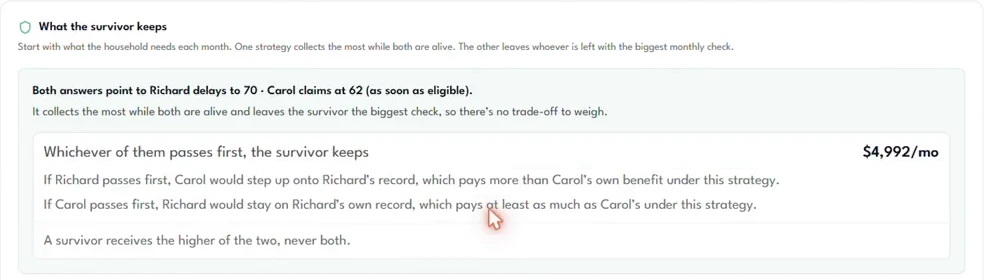
Together they collect $6,718 a month. When one spouse passes, the household keeps $4,992.
Every monthly claiming age from 62 to 70, computed in code — not generated by a large language model (LLM).
SOC 2 Type I report issued. Type II examination under way.
A Registered Social Security Analyst® available on complex cases.
One-click earnings record with our Chrome extension — live on the Chrome Web Store.
The whole appointment, in under two minutes
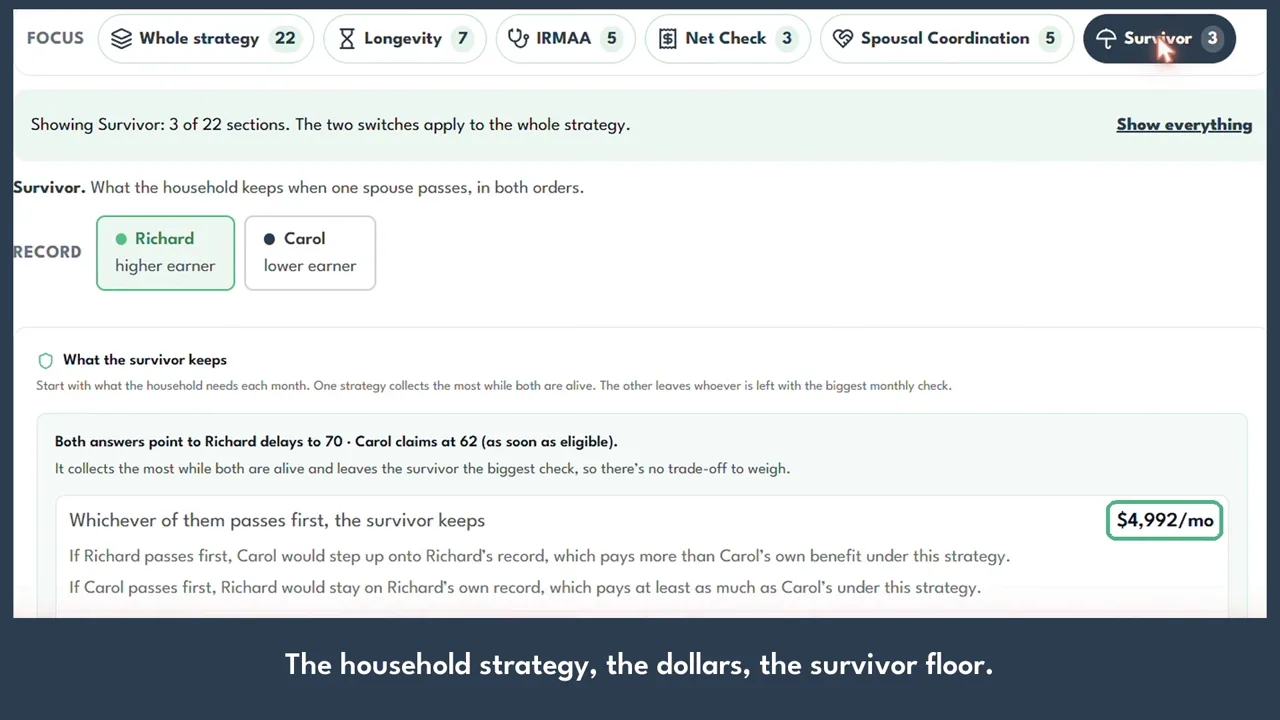
The client sends their earnings record in one click, the household strategy runs, and the report goes home with them. The survivor floor is at 0:57: what the household keeps when one spouse passes.
License walkthrough · 1:40 · music, captioned on screen · transcript below the video.
Transcript
The walkthrough has music and on-screen captions, with no voice. It runs 1:40, and every household in it is sample data.
It opens on an advisor firm’s pipeline: five households with completed analyses. The advisor invites a new client, who lands on the pipeline as Invited, and the invite email comes from the firm. The client then sends their Social Security earnings record in one click.
Next comes a married household’s recommended strategy: Richard delays to 70 and Carol claims at 62, $6,710 a month combined and $3,674,221 over the household’s lifetime, with a survivor floor of $4,992 a month. The net check shows what lands after federal tax and the Medicare Part B premium, and the IRMAA guard flags Medicare premium exposure.
The advisor downloads the branded client report, then goes back to the pipeline for the next household. It closes on the license: one license for the whole book, with Professional covering 25 households a year.
The software has no opinion about products and never will. Product selection stays with you.
What is behind the number
The survivor view, on screen
What the household keeps when one spouse passes: the larger check stays, the smaller of the two checks stops. Sized against the real record, not a rule of thumb.
Every month, 62 to 70, both spouses
Every monthly claiming age against the household’s record, across three planning horizons, computed in code — the survivor floor rule included.
A tailwind, not a warning
WEP and GPO were repealed in January 2025. SSA paid $7.5 billion to 1,127,723 people, an average of $6,710 (SSA release, March 2026).
A first client who is one of you
A Medicare-and-annuity producer is our first paying advisor client.
Three steps to a Social Security practice
Add a Social Security claiming review to your practice.
You run and deliver the analysis in a few clicks.
Offer it to your book.
Pre-built outreach templates and a seminar talk track announce the new service.
Show each household its own numbers.
The bridge income they need if they wait to claim, where an annuity fits. The income that stops when a spouse passes, where life insurance fits.
Clients come to you for a Social Security answer, and the case comes with it.
Where each conversation happens, in the product
Richard and Carol, the sample couple, as an advisor sees them. One screen for the floor, one for the bridge, one for the survivor.
1. The guaranteed income
The Social Security floor, for life
The recommended strategy: Richard delays to 70 and Carol claims at 62. Once both checks flow, $6,718 a month, for life, with a cost-of-living raise each year.
2. The annuity conversation
The bridge, before he claims
Household income, phase by phase. Until Richard files at 70, the household has no Social Security at first, then only Carol’s $600 a month. Those years need income from somewhere, and an annuity fits.
3. The life insurance conversation
The survivor gap, in both orders
Whichever of them passes first, the survivor keeps $4,992 a month. Together they collect $6,718. Life insurance fits that drop.
Screens from the MySSAgent advisor dashboard, sample data. Phase amounts include a 2.4 percent yearly cost-of-living increase from today, so later phases are in future dollars.
What it pays
The claiming date sizes the income gap. Get the date right first, and the product conversation starts from a number the client can see rather than a number you assert.
$1,990
Professional, 25 households a year — about $80 each.
5
analyses billed at the published floor of $400, and the license is paid for.
Your number
Ask what one placed annuity pays you, then set it beside the license.
The analysis runs before any product, so the recommendation is one you can defend. Both gaps are on the screen before anyone mentions an annuity or a policy.
Analysis fees are published advisory rates, which start at $400. Capacity above 25 households is priced on a call. The arithmetic is ours and checkable.
Free for producers
Two one-page tools for your client reviews and your next event. Print them and share them with your team.
- PDF, open downloadThe Book ScanFive questions to run against your own book. No account, no software, ten minutes.Download the PDF
- PDF, by emailThe Social Security 101 talk trackWhat to say when someone at your Medicare 101 asks when to take Social Security, and how to run the one-on-one after.Get it by email
Compared with how it happens today
| What the client sees | "Call SSA" | Generic calculator | In your appointment |
|---|---|---|---|
| The survivor line, sized against the real record | — | — | Yes |
| The bridge before a delayed claim, year by year | — | — | Yes |
| Both spouses, every month from 62 to 70 | — | Partial | Yes |
| Someone they already trust, licensed to advise on it | — | — | You |
Who this is not for
Anyone who wants the software to recommend a product — it has no opinion about products and never will. Anyone who wants a survivor figure without the household’s real record.
What producers ask first
"Best-interest rules — I can't have software steering product."
It doesn't. The tool sizes the household's Social Security income gap and has no opinion about products. Product selection stays with you.
"Overstating a survivor gap makes me look worse than skipping it."
Agreed — which is why the survivor floor rule (82.5% of PIA when the deceased claimed early) is in the code, not in someone's head.
"My clients already have a planner."
Most planning stacks treat Social Security as a single tab and never show the survivor line. You're adding the number nobody has shown them, not replacing anyone.
"How is this different from the free calculators?"
Free calculators compare whole ages for one person. This runs every month from 62 to 70 for the household, against the real record, and puts the survivor view and the net-benefit view on screen.
"Prove it."
Open the survivor case in the live demo. If the conversation isn't obvious in five minutes, close the tab — nothing follows you.
Reading for annuity producers
Sourced explainers on the Social Security rules that sit next to an income annuity.
- Social Security Software for Annuity Producers (2026)Ten claiming tools an insurance agent or annuity producer can use, each described from its maker's own website, with prices and a bridge-income example.
- Annuity Income and the Social Security Earnings TestSSA counts wages and net self-employment profit against the check before full retirement age, not annuities or pensions; the 2027 limits and the credit-back at full retirement age.
- The First Check Isn't the Whole RaiseDelayed retirement credits earned in the filing year are added the following January, so the first check reads lower than the all-credits estimate.
- The Spousal Top-Up After Claiming Social Security EarlySSA keeps paying the reduced own benefit and adds the excess spousal amount once the higher earner files, reduced from the month the top-up starts.
- The Widow's Gap: A Plan Has to Survive the First DeathDrop 05 — on day one of widowhood the household drops a Social Security check. The plan has to absorb it.
- How to Download Your Social Security Statement (XML)Twelve screenshots from ssa.gov sign-in to the XML file, then five checks for your earnings record, starting with zero years.
See both gaps in the demo
Three fields. Straight into the sample couple: the bridge, and the household after one spouse passes.